Crypto has spent some time trying to make unfamiliar money seem like second nature. Old money has had rather longer to get under our skin.
British financial advertising in the late 20th century was much more entertaining than it needed to be. Which might have been a clue. We learned the lessons. We were rather hazier about the products.
As a result, we grew up appreciating Mostyn as the smarter investor at the Alliance & Leicester, and could see that Stephen Fry, for all his braying and crowing and free medallion, had backed the shot horse at Sproggit and Sylvester.
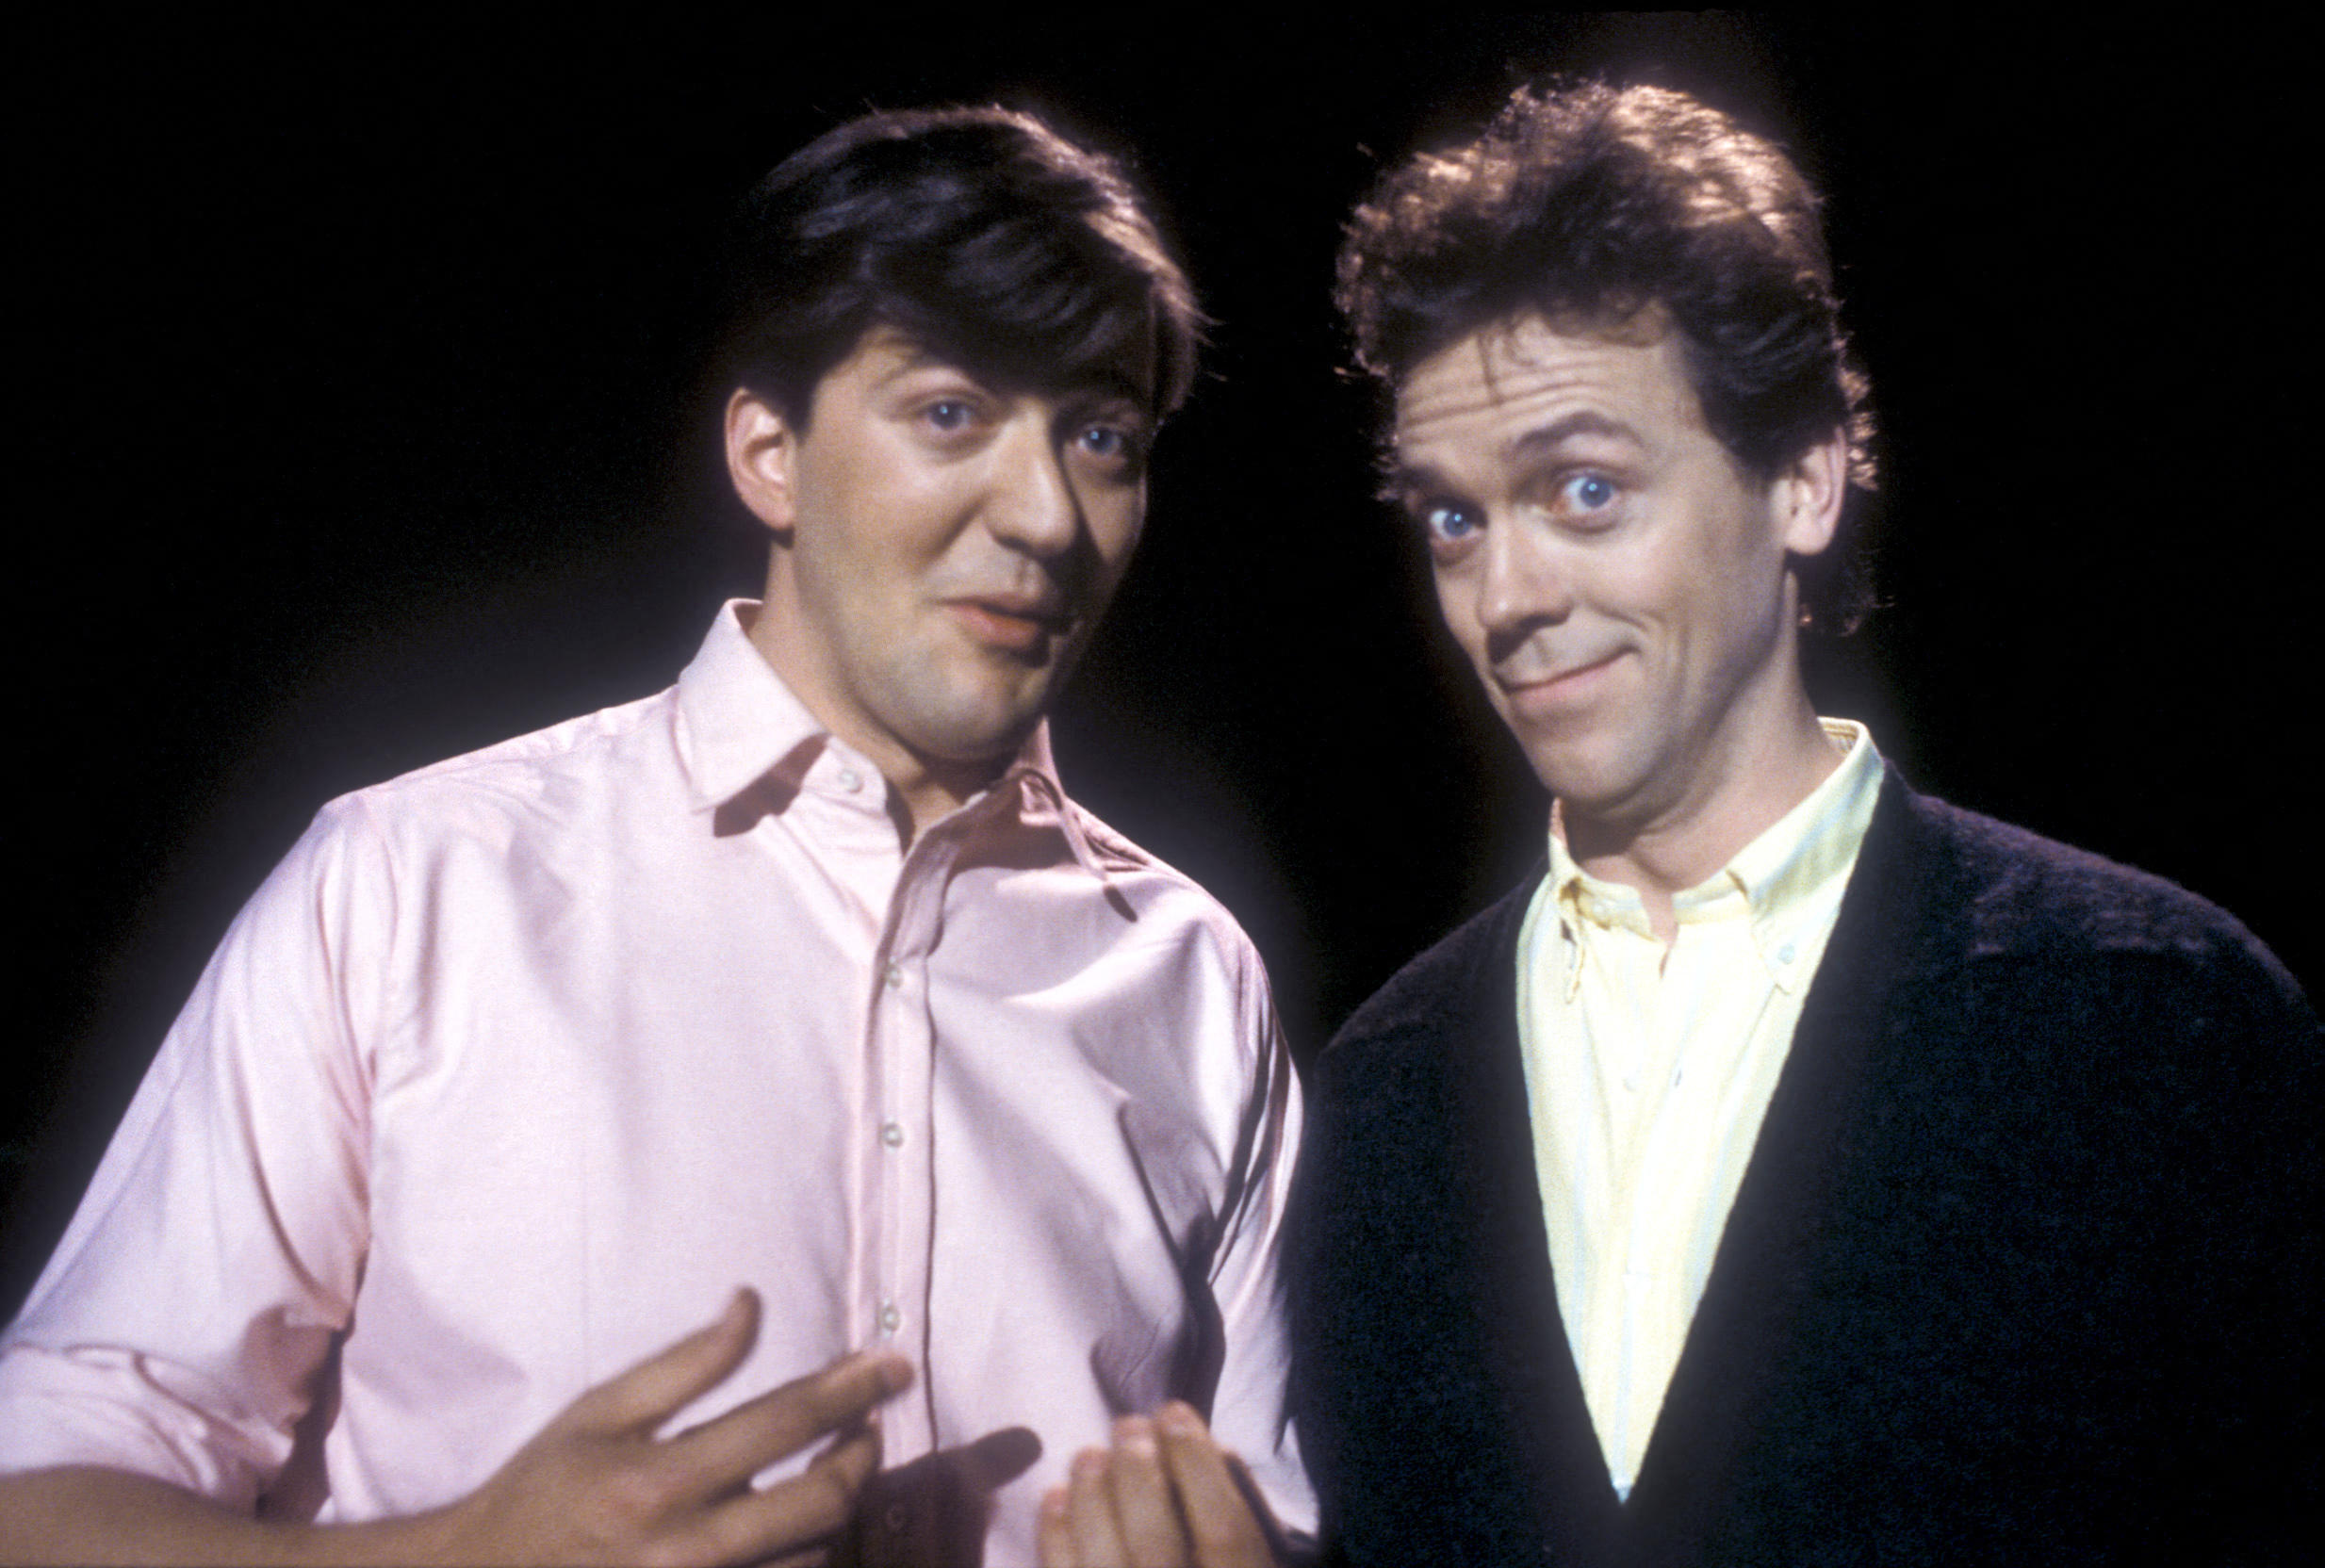
Stephen Fry and Hugh Laurie in A Bit of Fry and Laurie, 1987–95. BBC / Everett Collection Inc / Alamy
We knew, too, that Boff (Bough, apparently) couldn’t really smell those Tuareg campfires, unmistakable though they were. Latham’s rug had caught fire. Bough had insured his.
And we discovered that Scottish Widows liked to gather on clifftops, mystical and silent, to mourn departed husbands.
Smith and Jones in conversation at Nationwide Anglia. A thoroughly past-caring Victor Meldrew at Abbey National. Les Dawson for Premium Bonds, gossiping about the next-door neighbour’s tufted shag. At more than one point, a remarkable number of Britain’s light entertainers were kept afloat by mortgages, current accounts, and credit cards.
It didn’t last. Barclaycard’s spy escaped to Hollywood and became Johnny English. The Scottish Widow was flattened into a red digital silhouette, better suited to an app. Ads moved on to zooming red telephones, meerkats and, for reasons best known to the Halifax, Howard.
The £38 billion punchline
Nostalgia is selective about what it keeps. The Financial Services Authority fined Alliance & Leicester £7 million in 2008, then a record of its kind, for the most serious failings it had found in payment protection insurance sales. Staff had been trained to pressure customers who asked why PPI had appeared in their loan quote.
The Financial Conduct Authority eventually put PPI redress at more than £38 billion and called it the largest consumer payback exercise in UK history. Arnold Schwarzenegger fronted the campaign, urging people to claim before the deadline, or else he’d… I forget what it was.
Some irony, though, that the era’s last great celebrity-led financial campaign belonged to the regulator, clearing up after the others.
Familiarity is powerful stuff. In 1968, psychologist Robert Zajonc named something advertisers already understood: the mere exposure effect. The more often we encounter something, the more warmly we tend to regard it. In finance, recognition has another useful quality: it can feel like knowledge.
Deposit protection and regulation kept banks safe, though few customers could have said how. The adverts made sure nobody wondered. Familiar faces sold familiar names until it all became part of the furniture. You didn’t need to know how a payment cleared, where the bank put your money overnight, or much at all about what happened behind the counter. £50 was £50. You wanted it to get where it was going and, if something went wrong, you wanted somebody to give it back.
Successful financial infrastructure eventually disappears from view. We stop asking how it works. New money has the opposite problem.
Act natural
Crypto insists on showing us its backside. Wallets, keys, chains, and custody are on display, with customers expected to look after them personally. If the key goes, the money goes with it.
In 2013, James Howells threw out a hard drive holding the key to 8,000 bitcoin. It went to Newport’s council landfill and has stayed there ever since. In January 2025, the High Court dismissed his claim against the council as having no realistic prospect of succeeding, a decision subsequently upheld by the Court of Appeal.
Banks have spent decades keeping that sort of machinery out of sight. Crypto could only do the same by handing the keys to someone else, which defeated the object. Its advertising went searching for familiarity instead.
In 2021, Luno advertised on the London Underground with a cartoon bitcoin and the line “If you’re seeing Bitcoin on the Underground, it’s time to buy.” The Advertising Standards Authority banned the campaign. The heart of its ruling was that consumers were likely to understand the advert as suggesting bitcoin investment was straightforward and accessible, without appreciating that it was unregulated. Coinfloor went further, trying to pitch bitcoin to pensioners as a safe place for their savings.
Coinbase even tried a musical. In the ad, cheerful Britons sang that everything was fine as the lights went out and a sewage pipe burst around them, with crypto offered as the way out. The broadcasters’ vetting body turned it down for television, so it ran online and on the Underground instead, until the ASA banned it in January 2026.
Jokes were back, only now the regulator wasn’t laughing.
Recognition is the easy bit
Crypto is no longer obscure: the FCA’s latest consumer research found that 91 per cent of UK adults had heard of it.
Understanding is another matter. Only half of people who own or have owned crypto think they understand how it works and the technology behind it, down eight points from the year before. Among those who neither own crypto nor plan to buy any, the most common reason is that they don’t understand it.
Stablecoins are meant to be the sensible end of crypto: increasingly issued by regulated firms, usually held by a provider rather than with a key in a drawer, and tied to money people already use. But they still inherit crypto’s reputation. Among crypto users who hadn’t bought one, 39 per cent said they didn’t know enough about them, and another 28 per cent were unclear what they were for. Asked what would make them more likely to use one, the most common answer, from just over a quarter, was FCA regulation.
Which may be why the name matters so much. Stablecoins borrow familiarity from money itself: stable, pegged, one for one. The word does a good deal of reassuring before anybody needs an explainer.
In sterling, they barely exist yet. At the end of last year, they accounted for less than $6 million of a stablecoin market worth around $308 billion, almost all of it in dollars. The Bank of England intends to finalise its rules for the larger ones by the end of this year.
For now, “sterling” is carrying most of the weight.
The banks are back
Around 2019, some of the best-known names in banking lined up behind blockchain networks for letters of credit and trade documents, and by the end of 2023 most of those networks had gone. Insolvency claimed we.trade in June 2022 and Marco Polo the following February. Contour ran out of money that November.
A blue-chip shareholder register turned out to be no guarantee of survival. This time the banks have kept the ledger and left the coin at home: tokenised deposits are blockchain with the crypto taken out, the alcohol-free lager of digital money.
In 2025, UK Finance brought six banks together to test tokenised versions of the pounds in customers’ accounts. Quant provided the technology, and Monzo joined this January. Last month, Lloyds, NatWest, and Barclays used the system to complete two remortgages for live customers.
The scheme is called the Great British Tokenised Deposit, which sounds a bit like it involves a tent, a stopwatch and somebody being sent home. Barclays, HSBC UK, Lloyds, Monzo, Nationwide, NatWest and Santander make up the group. Three digital bond issues are planned for early 2027.
The same instinct showed up at Sibos last month. Swift’s chief executive, Javier Pérez-Tasso, said its blockchain-based ledger was “live and in use by some of the largest institutions in the world”, with at least 19 banks expected to use it by year-end for round-the-clock payments in tokenised deposits.
Nationwide once had Smith and Jones. Lloyds owns Scottish Widows. Santander has acquired Abbey National, Bradford & Bingley, and Alliance & Leicester over the years, and added TSB in May.
The old cast is back together, and the familiarity came with it. Banks can buy it, as Santander did, or inherit it. Lloyds’ black horse first hung outside a goldsmith’s on Lombard Street in 1677, and came to the bank in 1884 when it took over the business.
That is a long time to become familiar .
Not everyone in the cast has a century behind them. Monzo, founded in 2015, now has 15.2 million customers and says 79 per cent of them joined by word of mouth. It got there with a coral-coloured card in millions of wallets and an app that 10.4 million people use every month.
Boring may be the killer feature
The banks’ pitch for tokenised deposits is the one British banking has always made: your money is safe with us. UK Finance says tokenised deposits keep the regulatory protections of an ordinary deposit, the same ones that cover the money in your current account.
Forget the ledger technology for a moment and the message hasn’t changed in a century: this is the money you already know. Nothing here will surprise you.
That leaves stablecoin issuers with a peculiar problem. They can borrow sterling’s name. They can borrow reassurance from regulation. They can get themselves into apps people already open every day. They may even have the edge on sending money across borders. What they can’t readily borrow is time.
And perhaps that matters more in payments than almost anywhere else. Nobody joins a supermarket till hoping for a more interesting settlement rail. The ambition for new money is eventually to become as unremarkable as the old sort: accepted, quick, and sufficiently trusted that we stop wondering what is happening underneath.
Television schedulers have been running a similar experiment for years. Every Christmas , we say we want something new, then settle happily in front of the repeats, even the ones we know end badly.
That ought to be good news for the banks. Crypto, meanwhile, needs its own black horse. Lloyds has had one since 1884, and it has never once had to explain a ledger.