A year before the EU, the UK, and Switzerland move to next-day settlement, BNP Paribas’s Camille Papillard, Deputy Head of Financial Intermediaries & Corporates Client Line for Securities Services, explains why the hard work happens before midnight, and why Europe cannot simply copy America’s homework.
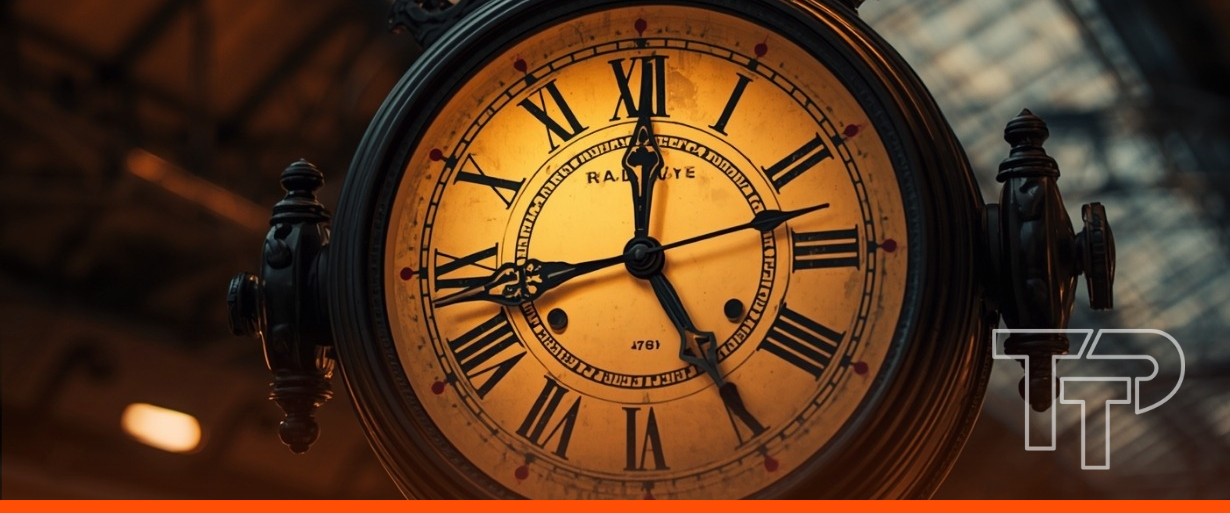
Above the door of the Exchange on Corn Street in Bristol hangs a clock with two minute hands, set about ten minutes apart. One shows Bristol’s own time, which runs behind London’s because the city sits further west. The other shows London time, which the Great Western Railway adopted for its timetable in November 1840. For several years the city lived by both, so a train timetabled to leave Temple Meads at noon left at ten to twelve by Bristol’s own time. Bristol officially adopted Greenwich time in 1852. The extra hand is still there.
Europe’s securities markets are a year from their own railway-time moment. On 11 October 2027, the EU, the UK, and Switzerland will move together from T+2 to T+1, cutting a day from the time between trade and settlement. To make room, the TARGET2-Securities night-time settlement cycle is being moved from around 20:00 to midnight CET, and EU rules will expect settlement instructions by 23:59 CET on the day of the trade, where feasible.
Camille Papillard, who is responsible for the products and solutions offered to bank, broker, and corporate clients at BNP Paribas’ Securities Services business, plays a pivotal role in the bank’s T+1 programme. On paper, the change looks modest, she said. “It’s a compression of the time between trade date and settlement date, so it’s a compression by a day. But in reality it’s even more than this, because you need to do things on trade date, which compresses from two days to a few hours.” BNP Paribas estimates that firms currently have 12 to 14 hours to manage their settlements and will soon have a few, which Papillard called “an 80 per cent reduction in time”.
Europe has 32 timetables to reconcile
America moved to T+1 on 28 May 2024, but with one currency and centralised settlement through the Depository Trust Company. Europe, which Papillard uses as shorthand for all three initiatives across Europe, the UK, and Switzerland, is much more fragmented. “We’re talking about 32 markets. We’re talking about 34 CSDs, 20-plus central clearing houses, over 300 trading venues, and 14 currencies,” she said. Each is driven by its own national authorities, tax rules and operating terms. Alongside the euro, sterling and the Swiss franc run around ten more currencies, each with a central bank setting its own cut-offs. “It’s not just a change,” she said. “It’s also a massive coordination effort.”
In Europe, being late also costs money. Under the Central Securities Depositories Regulation, late matching or a failed settlement brings a cash penalty, and with less time to prepare, the chances of failing go up.
Settlement turns out to be the easy part
Between the trade and the midnight batch sit allocation, confirmation, matching, funding and, sometimes, the recall of lent securities. The EU industry roadmap wants allocations and confirmations done by 23:00 CET on trade date. “In a way, the settlement itself is the easy part,” Papillard said. “It’s everything that’s happening ahead of settlement that needs to be seamless.”
A trade that misses the night batch can still settle during the next day. What it misses is the netting that the batch performs overnight, which offsets obligations against one another so that far less cash has to move. “Night batches, it’s not for the beauty of batches,” Papillard said. For treasurers, she said, the benefit is that settling through the batch is “definitely consuming less liquidity”.
US firms added people to make T+1 work
The US figures look reassuring. The industry’s after-action report found nearly 95 per cent of transactions meeting the 9pm ET affirmation cut-off on trade date, up from 73 per cent at the end of January 2024. In its 2024 annual report, DTCC said fail rates held at 2 to 3 per cent after the switch. Papillard said some clients have concluded that “because the transition in the US went smoothly, it’s gonna be the same in Europe”, and a large part of BNP Paribas’s programme work is persuading them otherwise. Many US firms coped by adding people to their operations teams, she said, “but this cannot be a long-term answer”.
Asia has to work through the European night
For firms trading into Europe from Asia, the whole trade-date sequence has to finish before the European day ends, long after their own offices have closed. Papillard sees two pressures: staffing a settlement cycle that runs through the local night, and getting cash in the right currency to the right account on time. The roadmap wants FX trades submitted to CLS by midnight on settlement date. Custodians offer automated FX, and “execution to custody” arrangements let the broker pass a trade directly to the client’s custodian without anyone instructing it by hand. “The further you are, the more challenging it’s gonna be,” she said.
Firms are waiting on each other to get ready
A year out, most firms are engaged. The EU T+1 Industry Committee’s second readiness survey, run by The ValueExchange and published in June 2026, found 83 per cent actively engaged. It also found 64 per cent citing their dependence on counterparties and vendors as a core concern, up six points, and only 37 per cent getting good signals that their own clients and counterparties are preparing. A survey by Tokenovate found 83 per cent of post-trade professionals expecting to meet the deadline, while 32 per cent said they were fully prepared.
Papillard worries about the smaller firms that are only now waking up to the change, and about how much manual work remains elsewhere. Standing settlement instructions are her example. “If you don’t get yours right, and the ones of your counterparties right, you can’t match your trades, and your trades will never settle.”
T+0 will arrive before the cash to fund it
A new T2S “gating event” at 11:00 CET on settlement day, expected from June 2027, will gather flagged transactions, mostly same-day repos, so that they can still be netted. “It sounds much nicer than a batch, but it’s a batch,” Papillard said.
She expects round-the-clock trading and the growth of digital assets to bring T+0 “on the table quicker than we think”, though probably in five to ten years rather than three. Tokenovate’s respondents think it could be less than four years away. The obstacle is money. Settling every trade the moment it happens removes the netting that lets institutions settle large gross volumes with much smaller payments. “If you want to settle everything at the same time, today it wouldn’t be possible because the cash isn’t there,” she said. “Instant is different from T-zero, definitely.”
Outside the Exchange stand four bronze tables known as the Nails, where merchants counted out coins to close their deals from the late 16th century onwards. Bristol likes to claim them as the origin of paying “on the nail”, though the phrase probably lent them its name rather than the other way round. Either way, a deal settled on the Nails was T+0, with nothing to net. Papillard thinks Europe’s markets may eventually get there too. First they have to make midnight.